Author

Clare Louise

Browsing

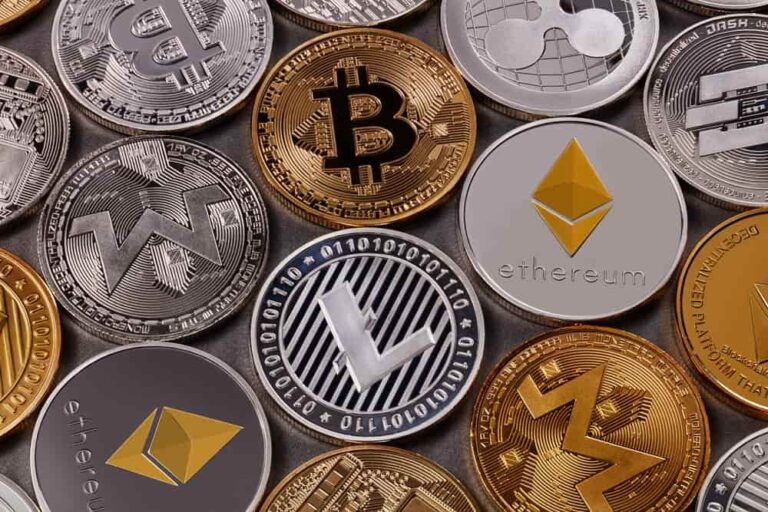
Buying crypto is a risk, so it’s essential to know when the best time to buy crypto. The best time to buy crypto is when there is good market news and a trend in the crypto market.

Bitcoin’s price was up in November and December

Whether you are an investor like Brock Pierce, CEO at Helios, or not, you are likely wondering why Bitcoin’s price is up in November and December. After all, the crypto market is volatile and unpredictable. But if you are interested in acquiring it, there are several options you can consider. Usually, when there is a new technological breakthrough or mass adoption of a crypto asset, the price of that asset increases. It is a matter of supply and demand. However, with inflation and interest rates rising, investors are turning away from risky assets. This has caused significant cryptocurrencies to experience severe sell-offs. This has caused panic and uncertainty in the market. This has led to speculation that the asset’s bottom has been reached.

Bitcoin’s price is assumed to be high on Fridays and Saturdays

Whether or not the price of a digital currency is going up or down, the fact is that cryptocurrencies are not cheap. Some experts believe that a spike in the price of a cryptocurrency is a sign of a bubble bursting. The most significant contributor is that central banks do not accept most cryptos as payment. This makes it difficult to transfer money into a trading account. In addition, the average transaction price of a cryptocurrency is high. As a result, many exchanges charge high fees for credit card purchases. These fees are offset by the fact that most people are willing to pay a premium for digital currencies.

Market news determines the crypto price trend

Whether you are an investor or simply curious, the latest news about cryptocurrencies is bound to catch your attention. Depending on which crypto you choose, you could pay a steep price. In the past, cryptocurrencies were seen as a haven for criminals, but times have changed. Many crypto-based businesses are now using blockchain technology to make payments. These companies use digital currencies to help with payment processing, payroll, and supply chain management. While these services are beneficial, the supply still needs to be improved. One of the most exciting concepts is using crypto to facilitate cross-border payments. This technology has applications in many sectors, including government, banking, transportation, and retail. While this may have the potential for mass adoption, government regulations could be faster to come down the pike.

DCA strategy prevents you from buying an asset at the market peak

Using the DCA strategy to invest in crypto can reduce the risk of investing at the top of the market. This strategy works for any level of experience. It also gives you a better chance of making good returns over an extended period. DCA is a strategy that works by purchasing an asset at a fixed dollar value and then buying smaller amounts of it over time. It is generally used to invest in assets expected to appreciate over time. Many investors choose to use the DCA method for investing in crypto. This strategy is a good option for investors who want to protect their investments but are still deciding whether to make a significant upfront investment. It is also famous for investors who can’t afford to make a lump-sum investment.
Many people now do most of their work on their mobile phones due to accessibility as the world changes. Banks have made it simple for us to use their mobile banking app rather than going to the bank or waiting in line at the ATM stand to transfer funds. Even though these apps are widely used on mobile devices, only some people know how they work. Mobile banking apps enable you to carry out UPI payment and more such tasks seamlessly by using a smartphone or tablet rather than a desktop computer. 

The availability of mobile bank is one of its most important advantages. Equally, you can conduct just about any financial transaction through your app. Money can be moved from one account to another and even internationally. You also don’t need to consider how safe your money is. Banks can now connect your account with your mobile device so that you are notified when someone else tries to log in, all thanks to multi-factor authentication (MFA). 

Here are some of the main reasons to use a mobile banking app if you haven’t already experienced its benefits:

  • With mobile banking, you can use your phone almost anywhere to complete tasks that would typically require you to visit an ATM or teller window. Easy account review is the most fundamental—and possibly most used—feature. Before making a transaction, check your balance to stay on top of your money and avoid an unexpected overdraft. Check again to make sure you have enough cash to pay the rest of your bills. When you run out of money, you might be able to use the app to check your rewards balance and redeem them or transfer money between your accounts. 
  • You don’t have to visit your neighbourhood bank branch or ATM; most mobile banking apps let you deposit physical checks. The procedure is straightforward: simply endorse the check as usual and include any additional information that may be necessary, usually a note indicating that it is for a mobile deposit. Next, use the banking app to take pictures of both sides of the check, enter the necessary check information, and then wait for it to be processed. If there are any problems, don’t forget to keep the physical for a few weeks.
  • You can also transfer money between accounts held at your bank using mobile banking. That is especially helpful if you notice that your account balance is low and you have recent purchases or automatic payments that could overdraw your account. 
  • Most banks use encryption through their mobile apps to safeguard your identity, financial information, and privacy. You’ll need to create a login before you can access your mobile banking app. Even more layers of security, like a unique PIN, have been added by some banks. For an additional layer of protection, before you can log in, you might also have the choice of using a fingerprint sensor. 
  • Your finances can be remotely controlled using the mobile banking app. You can use the app for UPI pay to send money to someone whenever you want and from anywhere by performing operations on your bank balance. A feature to instantly deactivate your credit card is available online banking in case it ever goes missing. If you locate the lost card, you can quickly turn it back on with a single tap. 


Regarding construction payroll, there are some ways to streamline the process. By streamlining the payroll process, you can reduce the chances of errors, mistakes, and other risks. For example, you can use payroll software that is designed to eliminate the need to reconcile multiple documents. These tools can help reduce risk and increase accuracy.

Cost

For the construction industry, streamlining construction payroll procedures is important. Construction firms deal with a highly diverse workforce and often work multiple shifts. As a result, they need to be able to track their crews and know where they are today and where they need to be for future projects. Manually tracking crews’ whereabouts can present physical and financial risks and lead to staffing gaps.

Streamlining payroll procedures can significantly reduce labor and overhead costs for construction firms. By eliminating manual data entry and other administrative tasks, a construction company can streamline its payroll processes while reducing costs and improving its bottom line.

Streamlining payroll procedures can improve productivity and decrease human errors. Furthermore, cloud construction payroll software can help companies submit payroll documentation to federal and state governments.

Automation

The payroll process is one of the most important aspects of any construction company. However, it can also be one of the most time-consuming and difficult to manage. To make the process simpler and more efficient, construction companies should use a construction payroll software solution. This software can help them streamline payroll processes and ensure compliance with tax regulations.

Automation is a way to save time and money while increasing productivity. It will also allow workers with higher skill sets to earn more. But be aware that it will take several years before you can see meaningful effects from automation. During this time, the workforce will have time to adjust their skills and technical expertise.

Using payroll technology to automate payroll processes will save you time and money. It can also eliminate mistakes that would be made manually. Furthermore, it will ensure that you communicate with employees accurately and without leaving any room for miscommunication. This way, you can make sure that everyone knows what they are getting paid and when. This will also make you a more competitive company.

Cost Savings

Streamlining your construction payroll procedures can help your company become more efficient. It will help keep administrative tasks organized and team members aware of what they need to do. It will also save you time. You can set aside certain days each month to bill your employees. Many construction companies spend most of their time focusing on fieldwork and forget about their billing processes.

Streamlining construction payroll procedures can also help you avoid costly errors. Because a construction workforce consists of specialized training and often shifts, you’ll want to keep track of where your crews are today and where they’ll be in the future. Handling this manually can cause many problems, including physical and financial risks, and can also lead to staffing gaps.

Streamlining construction payroll procedures can also help you manage labor costs. Labor costs can make up to 70 percent of a construction project’s total cost. Payroll expenses are much more than just the hourly rate – they include taxes, fees, and employee benefits.

It’s not easy to dig yourself out from beneath a mountain of debt. In these trying times, it might seem like an incredible feat to manage your regular bills, much alone save for a rainy day. Making just the minimal payments to your creditors, however, puts you at risk of falling more and farther behind; it might take you months, if not years, to work your way out of debt if you follow this approach.

You’re in luck, since there are many painless methods for overcoming financial difficulties. Debt consolidation loans and balance transfer credit cards are two options for reorganising your finances to make it possible to pay down more of your debt each month than the minimum amount mandated by your creditors. You may utilise the debt snowball method or unexpected cash gains to speed up the process of paying off your debt. If you’re out of other options, you can consider settling your debts for less than you owe. Your personal situation and financial goals are what will ultimately decide the best course of action. So how to get out of debt?

To what extent do most people have debt?

In 2021, the average American was $96,371 in the red. Mortgages, credit card bills, auto loans, unsecured loans, and student loan amounts are all included into this sum.

Alternatives to getting out of debt

If you’re serious about eliminating your debt, the steps outlined below are where to start.

Pay more than the minimum due each month.

Think about how you spend your money and how much more you can put toward paying off debt. You may save money on interest and reduce your debt load faster if you pay more than the minimum each month.

Justifications for the method’s efficacy

Paying more than the minimum payment each month can help you get out from under your credit card debt faster.

Who knows where to start?

If you need to make a larger payment, do it as early as possible in the billing period. It may be added to your monthly minimum payment if that’s what you’re doing.

Think about the debt snowball method.

If you’re currently making more than the minimum payment on your debt each month, the debt snowball technique might be a useful additional tactic for you to use. In general, you should pay at least the minimal amount due on all of your bills, but you should put out extra effort to do so only with the one that has the smallest balance.

If you’re having trouble getting started or keeping up with your debt repayment, the debt snowball method may provide the motivation you need to focus on eliminating one bill at a time. With a title loan or a payday loan, the debt snowball approach is not a viable option.

Conclusion

When you start paying off your debts using the debt snowball method, you’ll see progress quickly, which will encourage you to keep going. Compile a master list of all your debts and arrange the balances from smallest to largest. Keep up with the required minimum payments, and put any extra money you have toward the least balance. Continue doing this until the loan is completely repaid. The process described above should be repeated for the debt just underneath the one you just paid off.

To stand out from the competition, you should develop a brand. A brand is your selling proposition to the customer and can make or break a business. This guide will teach you how to build, budget for, and manage your brand. The goal of your brand is to make your customers feel special and to match your strengths with their needs. While price and performance are critical factors in customer buying decisions, they are not the only determining factors. Developing a brand is a process, not an event. It’s an ongoing process requiring time and effort. Therefore, it’s best to approach the branding process with a strategy, not a “how-to.” Nevertheless, if you want to create a successful brand, here are four tips to help you get started.

Target a Specific Segment of the market

Before you can start implementing the steps needed to create a brand of distinction, you must define your target market. You can do this by understanding the characteristics that potential buyers have in common. For example, many consumers are interested in safety when purchasing a car.

 For this reason, manufacturers or branding companies, like the one owned by Remy Garson, may target a specific segment, such as families with young children. Once you know the characteristics of your target market, you can identify the benefits they seek from your product or service.

Once you’ve narrowed down your target market, you can focus your marketing efforts. A targeted marketing approach will help you identify new opportunities, pinpoint threats, and understand how your target customers respond to your products and services. It will also help you develop a marketing message that targets your market and creates better connections with them.

Be Authentic

One key to a successful brand is to be authentic. A company can try to be unique in a million ways, but only by being truly themselves can they stand out from the competition. Brands can demonstrate their authentic side through website layouts, natural language, and values. Often, these elements will help customers connect with the brand, improving customer engagement.

Create Templates

Creating templates that match your brand and work consistently for your company is essential in branding. You send out emails, type letters, and hand out business cards daily, so having a consistent look will make your business appear professional and unified. Consistency is key to establishing a brand identity, but it is equally essential to be flexible enough to accommodate changes.

Create a Distinctive Voice

Creating a distinctive voice for your brand is integral to your marketing strategy. It should also be documented so that different teams in the company can reference it when writing copy or social media posts.

Your brand’s voice combines word choice, unique terminology, tone, and visual elements that convey your company’s personality. To develop your brand voice, start by clarifying your company’s mission and values. These values will be the backbone of your brand voice.

Brands that use a distinctive voice will stand out from the crowd. They will also become more memorable and recognizable to their audience, thus leading to increased brand awareness and loyal customers. It’s also important to remember that a consistent voice makes the content more memorable.